

13 A Critical Intertemporal Analysis of Uganda’s Fiscal Regime …
411
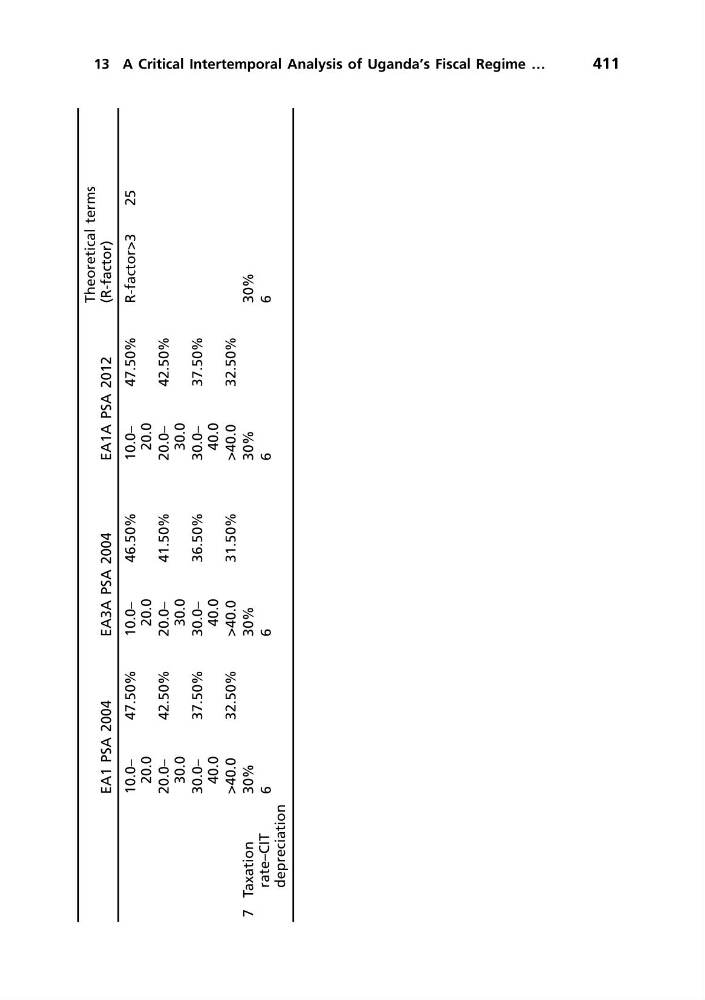
EA1 PSA 2004
EA3A PSA 2004
EA1A PSA 2012
Theoretical terms
(R-factor)
10.0–
20.0
47.50%
10.0–
20.0
46.50%
10.0–
20.0
47.50%
R-factor>3
25
20.0–
30.0
42.50%
20.0–
30.0
41.50%
20.0–
30.0
42.50%
30.0–
40.0
37.50%
30.0–
40.0
36.50%
30.0–
40.0
37.50%
>40.0
32.50%
>40.0
31.50%
>40.0
32.50%
7 Taxation
rate–CIT
depreciation
30%
30%
30%
30%
6
6
6
6