

84
S. Goto and H. Hino
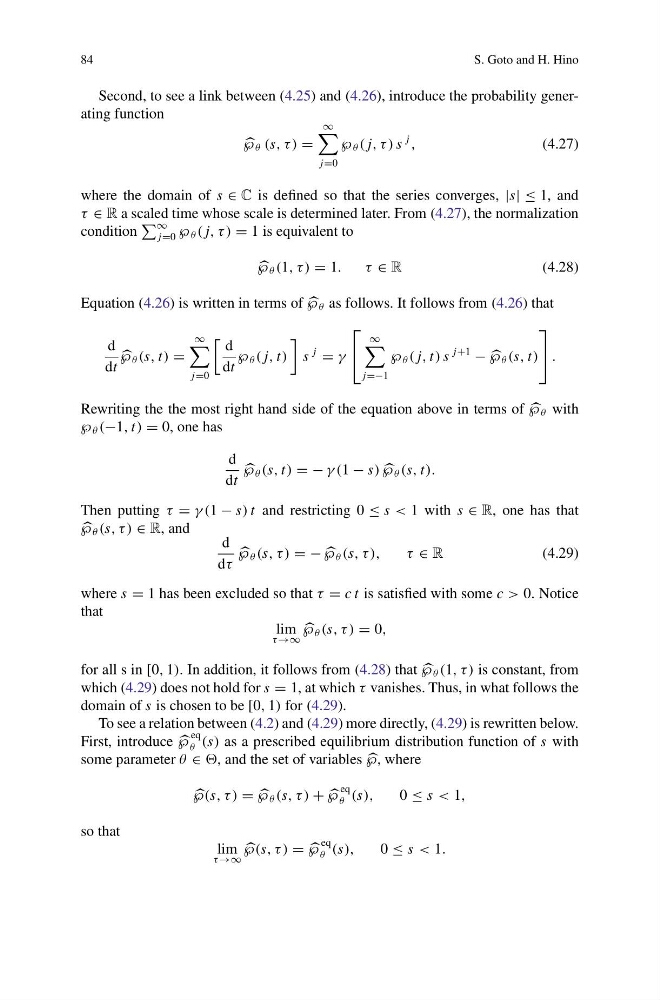
Second, to see a link between (4.25) and (4.26), introduce the probability generating function
℘ θ (s, τ ) =
∞
j=0
℘ θ ( j, τ ) s
j
,
(4.27)
where the domain of s ∈ C is defined so that the series converges, |s| ≤ 1, and
τ ∈ R a scaled time whose scale is determined later. From (4.27), the normalization
condition
∞
j=0 ℘ θ ( j, τ ) = 1 is equivalent to
℘ θ (1, τ ) = 1.
τ ∈ R
(4.28)
Equation (4.26) is written in terms of
℘ θ as follows. It follows from (4.26) that
d
dt
℘ θ (s, t) =
∞
j=0
d
dt
℘ θ ( j, t)
s
j
= γ
⎡
⎣
∞
j=−1
℘ θ ( j, t) s
j+1
−
℘ θ (s, t)
⎤
⎦ .
Rewriting the the most right hand side of the equation above in terms of
℘ θ with
℘ θ (−1, t) = 0, one has
d
dt
℘ θ (s, t) = − γ (1 − s)
℘ θ (s, t).
Then putting τ = γ (1 − s) t and restricting 0 ≤ s < 1 with s ∈ R, one has that
℘ θ (s, τ ) ∈ R, and
d
dτ
℘ θ (s, τ ) = −
℘ θ (s, τ ),
τ ∈ R
(4.29)
where s = 1 has been excluded so that τ = c t is satisfied with some c > 0. Notice
that
lim
τ →∞
℘ θ (s, τ ) = 0,
for all s in [0, 1). In addition, it follows from (4.28) that
℘ θ (1, τ ) is constant, from
which (4.29) does not hold for s = 1, at which τ vanishes. Thus, in what follows the
domain of s is chosen to be [0, 1) for (4.29).
To see a relation between (4.2) and (4.29) more directly, (4.29) is rewritten below.
First, introduce
℘
eq
θ (s) as a prescribed equilibrium distribution function of s with
some parameter θ ∈ , and the set of variables
℘, where
℘(s, τ ) =
℘ θ (s, τ ) +
℘
eq
θ (s),
0 ≤ s < 1,
so that
lim
τ →∞
℘(s, τ ) =
℘
eq
θ (s),
0 ≤ s < 1.