

48
1 Preliminaries
hold, then in the domain D, there must be f (x, y) ≡ 0.
Lemmas 1.5.3 and 1.5.4 can also be generalized to the situation of integral of the
function of n variables.
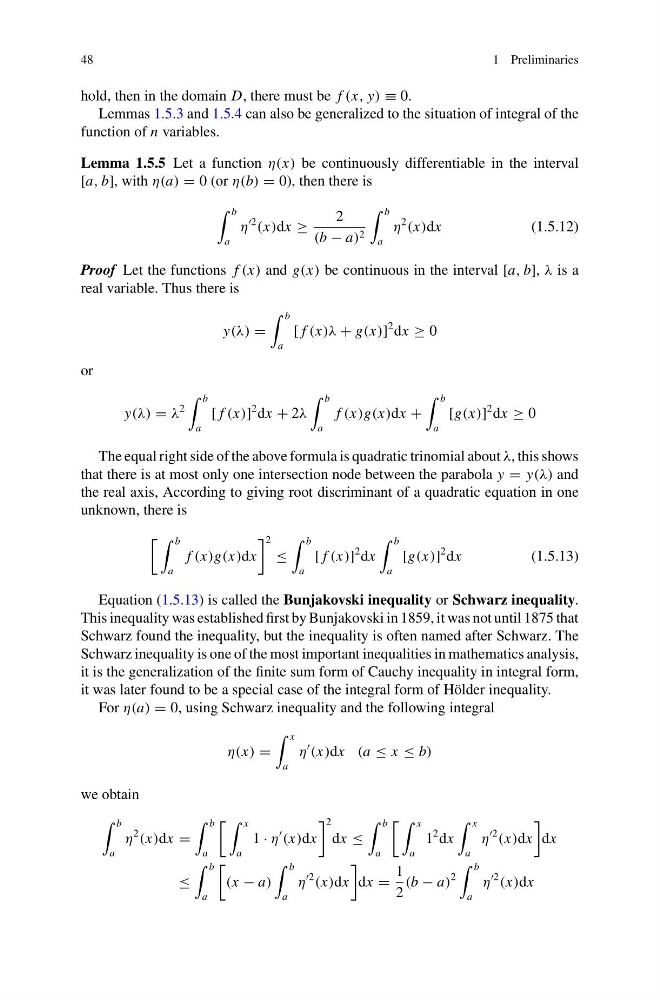
Lemma 1.5.5 Let a function η(x) be continuously differentiable in the interval
[a, b], with η(a) = 0 (or η(b) = 0), then there is
b
a
η
2
(x)dx ≥
2
(b − a) 2
b
a
η
2
(x)dx
(1.5.12)
Proof Let the functions f (x) and g(x) be continuous in the interval [a, b], λ is a
real variable. Thus there is
y(λ) =
b
a
[ f (x)λ + g(x)]
2 dx ≥ 0
or
y(λ) = λ
2
b
a
[ f (x)]
2 dx + 2λ
b
a
f (x)g(x)dx +
b
a
[g(x)]
2 dx ≥ 0
The equal right side of the above formula is quadratic trinomial about λ, this shows
that there is at most only one intersection node between the parabola y = y(λ) and
the real axis, According to giving root discriminant of a quadratic equation in one
unknown, there is
b
a
f (x)g(x)dx
2
≤
b
a
[ f (x)]
2 dx
b
a
[g(x)]
2 dx
(1.5.13)
Equation (1.5.13) is called the Bunjakovski inequality or Schwarz inequality.
This inequality was established first by Bunjakovski in 1859, it was not until 1875 that
Schwarz found the inequality, but the inequality is often named after Schwarz. The
Schwarz inequality is one of the most important inequalities in mathematics analysis,
it is the generalization of the finite sum form of Cauchy inequality in integral form,
it was later found to be a special case of the integral form of Hölder inequality.
For η(a) = 0, using Schwarz inequality and the following integral
η(x) =
x
a
η
(x)dx (a ≤ x ≤ b)
we obtain
b
a
η
2
(x)dx =
b
a
x
a
1 · η
(x)dx
2
dx ≤
b
a
x
a
1
2 dx
x
a
η
2
(x)dx
dx
≤
b
a
(x − a)
b
a
η
2
(x)dx
dx =
1
2
(b − a)
2
b
a
η
2
(x)dx