

(a) not more than the benefits obtainable from it,
(b) not more than the alternative cost, and.
(c) not less than the specific cost.
Apart these three basic principles, the national priority or urgency of any purpose
over others, at the time of formulating the multipurpose project, or during any future
review, should be duly considered.
19.4.3 Common Allocation Procedures
The different methods for cost allocation generally have a common procedure
described below in four steps:
(a) To determine specific costs which serve each of the purposes;
(b) To assign such specific costs to various purposes from the capital cost and to find
out the remaining joint cost;
(c) To distribute joint cost equitably to various purposes; and.
(d) To sum up, for each purpose, the specific cost and the share of joint cost
chargeable to that purpose.
19.4.4 Current Cost Allocation Methods
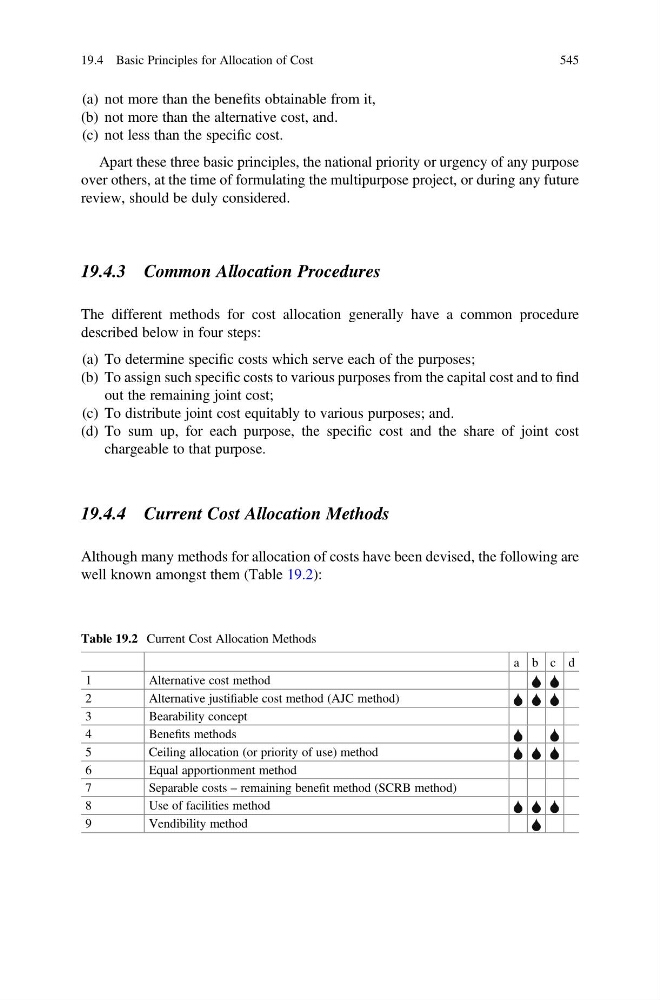
Although many methods for allocation of costs have been devised, the following are
well known amongst them (Table 19.2):
Table 19.2 Current Cost Allocation Methods
a b c d
1
Alternative cost method
2
Alternative justifiable cost method (AJC method)
3
Bearability concept
4
Benefits methods
5
Ceiling allocation (or priority of use) method
6
Equal apportionment method
7
Separable costs – remaining benefit method (SCRB method)
8
Use of facilities method
9
Vendibility method
19.4 Basic Principles for Allocation of Cost
545