

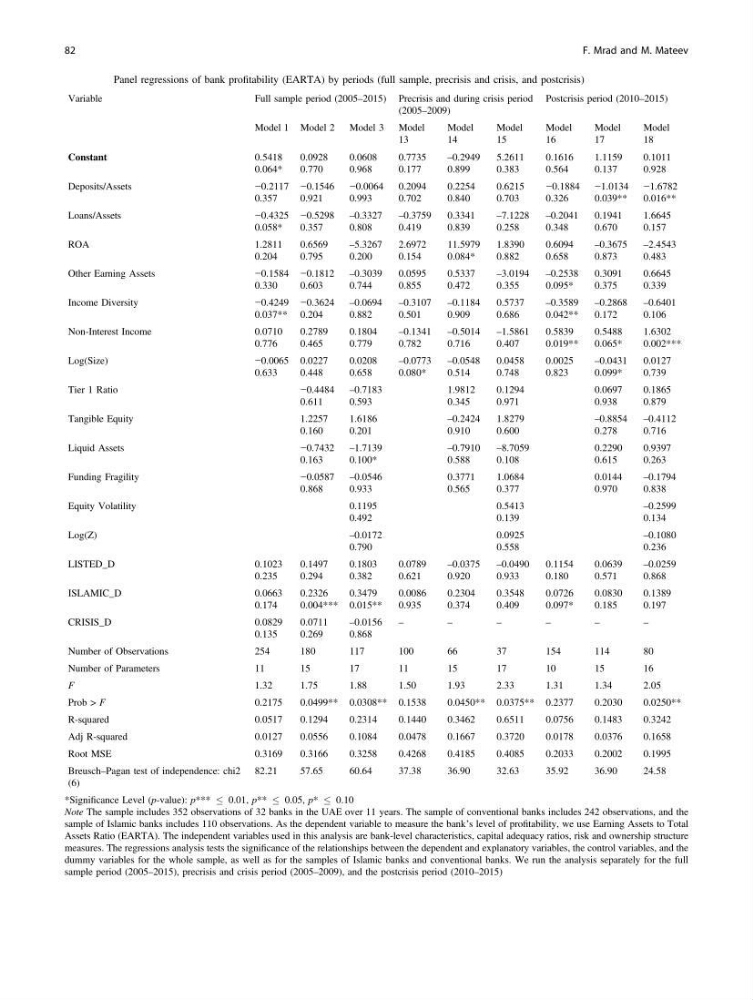
Table 11 Panel regressions of bank profitability (EARTA) by periods (full sample, precrisis and crisis, and postcrisis)
Variable
Full sample period (2005–2015) Precrisis and during crisis period
(2005–2009)
Postcrisis period (2010–2015)
Model 1 Model 2 Model 3 Model
13
Model
14
Model
15
Model
16
Model
17
Model
18
Constant
0.5418
0.064*
0.0928
0.770
0.0608
0.968
0.7735
0.177
–0.2949
0.899
5.2611
0.383
0.1616
0.564
1.1159
0.137
0.1011
0.928
Deposits/Assets
−0.2117
0.357
−0.1546
0.921
−0.0064
0.993
0.2094
0.702
0.2254
0.840
0.6215
0.703
−0.1884
0.326
−1.0134
0.039**
−1.6782
0.016**
Loans/Assets
−0.4325
0.058*
−0.5298
0.357
–0.3327
0.808
–0.3759
0.419
0.3341
0.839
–7.1228
0.258
–0.2041
0.348
0.1941
0.670
1.6645
0.157
ROA
1.2811
0.204
0.6569
0.795
–5.3267
0.200
2.6972
0.154
11.5979
0.084*
1.8390
0.882
0.6094
0.658
–0.3675
0.873
–2.4543
0.483
Other Earning Assets
−0.1584
0.330
−0.1812
0.603
–0.3039
0.744
0.0595
0.855
0.5337
0.472
–3.0194
0.355
–0.2538
0.095*
0.3091
0.375
0.6645
0.339
Income Diversity
−0.4249
0.037**
−0.3624
0.204
–0.0694
0.882
–0.3107
0.501
–0.1184
0.909
0.5737
0.686
–0.3589
0.042**
–0.2868
0.172
–0.6401
0.106
Non-Interest Income
0.0710
0.776
0.2789
0.465
0.1804
0.779
–0.1341
0.782
–0.5014
0.716
–1.5861
0.407
0.5839
0.019**
0.5488
0.065*
1.6302
0.002***
Log(Size)
−0.0065
0.633
0.0227
0.448
0.0208
0.658
–0.0773
0.080*
–0.0548
0.514
0.0458
0.748
0.0025
0.823
–0.0431
0.099*
0.0127
0.739
Tier 1 Ratio
−0.4484
0.611
–0.7183
0.593
1.9812
0.345
0.1294
0.971
0.0697
0.938
0.1865
0.879
Tangible Equity
1.2257
0.160
1.6186
0.201
–0.2424
0.910
1.8279
0.600
–0.8854
0.278
–0.4112
0.716
Liquid Assets
−0.7432
0.163
–1.7139
0.100*
–0.7910
0.588
–8.7059
0.108
0.2290
0.615
0.9397
0.263
Funding Fragility
−0.0587
0.868
–0.0546
0.933
0.3771
0.565
1.0684
0.377
0.0144
0.970
–0.1794
0.838
Equity Volatility
0.1195
0.492
0.5413
0.139
–0.2599
0.134
Log(Z)
–0.0172
0.790
0.0925
0.558
–0.1080
0.236
LISTED_D
0.1023
0.235
0.1497
0.294
0.1803
0.382
0.0789
0.621
–0.0375
0.920
–0.0490
0.933
0.1154
0.180
0.0639
0.571
–0.0259
0.868
ISLAMIC_D
0.0663
0.174
0.2326
0.004***
0.3479
0.015**
0.0086
0.935
0.2304
0.374
0.3548
0.409
0.0726
0.097*
0.0830
0.185
0.1389
0.197
CRISIS_D
0.0829
0.135
0.0711
0.269
–0.0156
0.868
–
–
–
–
–
–
Number of Observations
254
180
117
100
66
37
154
114
80
Number of Parameters
11
15
17
11
15
17
10
15
16
F
1.32
1.75
1.88
1.50
1.93
2.33
1.31
1.34
2.05
Prob > F
0.2175
0.0499** 0.0308** 0.1538
0.0450** 0.0375** 0.2377
0.2030
0.0250**
R-squared
0.0517
0.1294
0.2314
0.1440
0.3462
0.6511
0.0756
0.1483
0.3242
Adj R-squared
0.0127
0.0556
0.1084
0.0478
0.1667
0.3720
0.0178
0.0376
0.1658
Root MSE
0.3169
0.3166
0.3258
0.4268
0.4185
0.4085
0.2033
0.2002
0.1995
Breusch–Pagan test of independence: chi2
(6)
82.21
57.65
60.64
37.38
36.90
32.63
35.92
36.90
24.58
*Significance Level (p-value): p***
0.01, p**
0.05, p*
0.10
Note The sample includes 352 observations of 32 banks in the UAE over 11 years. The sample of conventional banks includes 242 observations, and the
sample of Islamic banks includes 110 observations. As the dependent variable to measure the bank’s level of profitability, we use Earning Assets to Total
Assets Ratio (EARTA). The independent variables used in this analysis are bank-level characteristics, capital adequacy ratios, risk and ownership structure
measures. The regressions analysis tests the significance of the relationships between the dependent and explanatory variables, the control variables, and the
dummy variables for the whole sample, as well as for the samples of Islamic banks and conventional banks. We run the analysis separately for the full
sample period (2005–2015), precrisis and crisis period (2005–2009), and the postcrisis period (2010–2015)
82
F. Mrad and M. Mateev