

8 A. Klitkou et al.
relate them to new processes or new products. Sometimes a bioeconomic
improvement may even need the combination of several different waste streams.
Such cross- cutting relations across the sectors can emerge at several stages
of the “value circle”. We prefer to adopt the expression “value circle”, rather
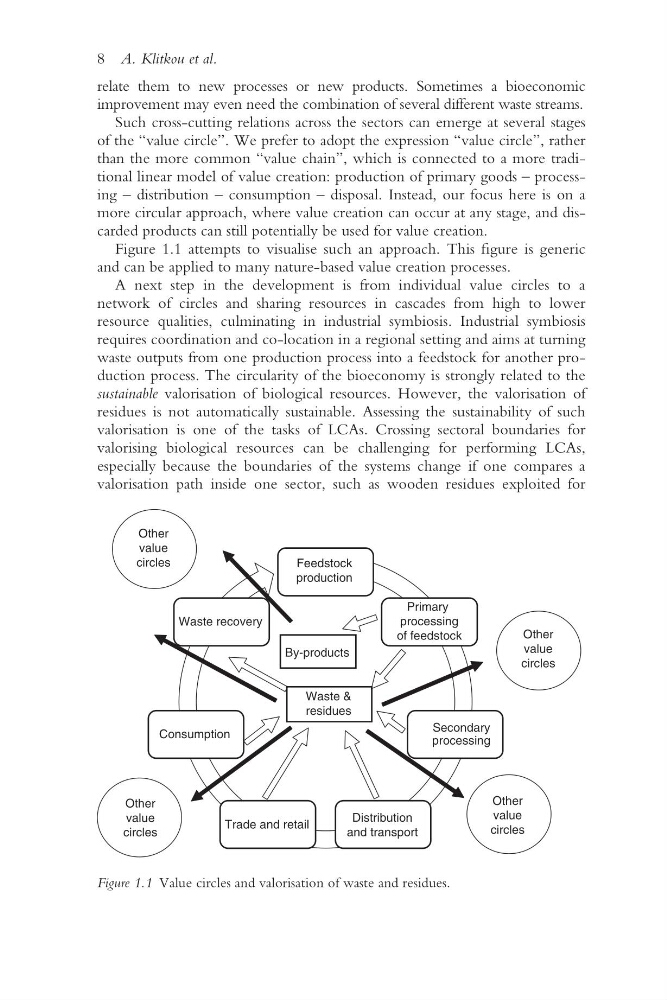
than the more common “value chain”, which is connected to a more traditional linear model of value creation: production of primary goods – processing – distribution – consumption – disposal. Instead, our focus here is on a
more circular approach, where value creation can occur at any stage, and discarded products can still potentially be used for value creation.
Figure 1.1 attempts to visualise such an approach. This figure is generic
and can be applied to many nature- based value creation processes.
A next step in the development is from individual value circles to a
network of circles and sharing resources in cascades from high to lower
resource qualities, culminating in industrial symbiosis. Industrial symbiosis
requires coordination and co- location in a regional setting and aims at turning
waste outputs from one production process into a feedstock for another production process. The circularity of the bioeconomy is strongly related to the
sustainable valorisation of biological resources. However, the valorisation of
residues is not automatically sustainable. Assessing the sustainability of such
valorisation is one of the tasks of LCAs. Crossing sectoral boundaries for
valorising biological resources can be challenging for performing LCAs,
especially because the boundaries of the systems change if one compares a
valorisation path inside one sector, such as wooden residues exploited for
Other
value
circles
Other
value
circles
Other
value
circles
By-products
Feedstock
production
Primary
processing
of feedstock
Secondary
processing
Distribution
and transport
Trade and retail
Consumption
Waste recovery
Waste &
residues
Other
value
circles
Figure 1.1 Value circles and valorisation of waste and residues.