

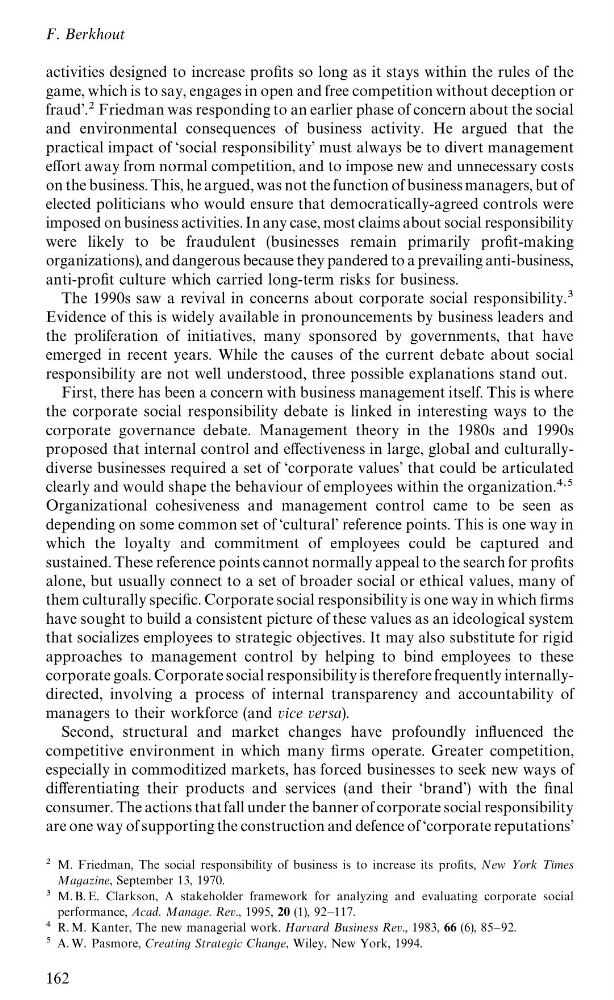
activities designed to increase profits so long as it stays within the rules of the
game, which is to say, engages in open and free competition without deception or
fraud’. Friedman was responding to an earlier phase of concern about the social
and environmental consequences of business activity. He argued that the
practical impact of ‘social responsibility’ must always be to divert management
effort away from normal competition, and to impose new and unnecessary costs
on the business. This, he argued, was not the function of business managers, but of
elected politicians who would ensure that democratically-agreed controls were
imposed on business activities. In any case, most claims about social responsibility
were likely to be fraudulent (businesses remain primarily profit-making
organizations), and dangerous because they pandered to a prevailing anti-business,
anti-profit culture which carried long-term risks for business.
The 1990s saw a revival in concerns about corporate social responsibility.
Evidence of this is widely available in pronouncements by business leaders and
the proliferation of initiatives, many sponsored by governments, that have
emerged in recent years. While the causes of the current debate about social
responsibility are not well understood, three possible explanations stand out.
First, there has been a concern with business management itself. This is where
the corporate social responsibility debate is linked in interesting ways to the
corporate governance debate. Management theory in the 1980s and 1990s
proposed that internal control and effectiveness in large, global and culturallydiverse businesses required a set of ‘corporate values’ that could be articulated
clearly and would shape the behaviour of employees within the organization.
Organizational cohesiveness and management control came to be seen as
depending on some common set of ‘cultural’ reference points. This is one way in
which the loyalty and commitment of employees could be captured and
sustained. These reference points cannot normally appeal to the search for profits
alone, but usually connect to a set of broader social or ethical values, many of
them culturally specific. Corporate social responsibility is one way in which firms
have sought to build a consistent picture of these values as an ideological system
that socializes employees to strategic objectives. It may also substitute for rigid
approaches to management control by helping to bind employees to these
corporate goals. Corporate social responsibility is therefore frequently internallydirected, involving a process of internal transparency and accountability of
managers to their workforce (and vice versa).
Second, structural and market changes have profoundly influenced the
competitive environment in which many firms operate. Greater competition,
especially in commoditized markets, has forced businesses to seek new ways of
differentiating their products and services (and their ‘brand’) with the final
consumer. The actions that fall under the banner of corporate social responsibility
are one way of supporting the construction and defence of ‘corporate reputations’
M. Friedman, The social responsibility of business is to increase its profits, New York Times
Magazine, September 13, 1970.
M. B. E. Clarkson, A stakeholder framework for analyzing and evaluating corporate social
performance, Acad. Manage. Rev., 1995, 20 (1), 92—117.
R. M. Kanter, The new managerial work. Harvard Business Rev., 1983, 66 (6), 85—92.
A. W. Pasmore, Creating Strategic Change, Wiley, New York, 1994.
F. Berkhout
162